
Summary
Equities were mixed this week, with the Dow leading at +0.96% and the S&P 500 gaining +0.40%, while the Nasdaq slipped -0.06%, as the 10-year Treasury yield edged down -2 basis points to 4.67%. Economic data was mixed, with New Home Sales rebounding +1.6% in June, durable goods orders rising +0.3%, and PCE softening as the year-over-year rate eased to +3.7% from +4.1%. Second quarter GDP disappointed, however, rising just +1.5% against a +2.0% estimate and decelerating from +2.1% in Q1, while Consumer Confidence slipped to 90.8 and Initial Jobless Claims rose to 197,000. At Wednesday’s FOMC meeting, the Fed held rates at 3.50% to 3.75%, with three members dissenting in favor of a hike; Chairman Kevin Warsh signaled the Fed could broaden how it assesses inflation beyond PCE, and traders continue to price in at least one rate hike by year end while paring back bets on a further hikes next year. On the corporate side, Microsoft (MSFT) surged +15% after posting +43% Azure growth, its strongest since 2022, adding a record $450 billion in market cap, while Royal Caribbean (RCL) increased +5% on strong demand and lower costs. On the downside, Corning (GLW) decreased -12% on soft revenue guidance, and Meta (META) declined nearly -8% after missing earnings expectations and guiding revenue lower, as its free cash flow plunged -91% year over year to $784 million amid heavy AI spending. Commodities were mixed, with spot gold rising +1.25% and spot silver climbing +1.43%, while Bitcoin gained +0.95%, the dollar fell -1.46% as inflation expectations rose post-FOMC, and WTI Crude declined -6% after the US and Iran paused strikes before hostilities resumed midweek.
10-Year Treasury Yield
- Current Rate: 4.67% (as of July 30, 2026)
- Week-to-Date Movement: -2bps (from 4.69% on July 23, 2026)
Major U.S. Equity Indices Performance
- S&P 500: 7,408.30 → 7,437.37 (+0.40% WTD)
- Dow Jones Industrial Avg: 51,711.65 → 52,208.06 (+0.96% WTD)
- Nasdaq Composite: 25,137.69 → 25,122.18 (-0.06% WTD)
Notable Market Events
Macroeconomic Data:
At the end of last week, New Home Sales rebounded +1.6% in June to 628,000 from 618,000 the prior month, recovering from a -4.3% decline in May. MBA Mortgage Applications fell -6.4% for the week ending July 24th, reversing the +1.9% gain the prior week. Preliminary durable goods orders rose +0.3% in June, led by computers and electronic products, following a -4% decline in May. The Conference Board’s Consumer Confidence Index slipped to 90.8 in July from 92.2 the prior month, as consumers anticipated little improvement in business conditions over the next six months, though expectations for the labor market were slightly less negative and income expectations moderated but remained optimistic overall. On inflation, PCE softened in June, falling -0.1% month over month, while the year-over-year rate eased to +3.7% from +4.1% the prior month. Second quarter GDP rose +1.5%, missing the street’s +2.0% estimate and decelerating from +2.1% in Q1, while Initial Jobless Claims edged up to 197,000 for the week ending July 25th from 188,000 the prior week.
Economic Policy:
The Federal Reserve held rates at 3.50% to 3.75% at Wednesday’s FOMC meeting, with three members dissenting in favor of a quarter-point hike. Fed Chairman Kevin Warsh signaled the central bank could shift how it assesses inflation, noting that he is monitoring a broader set of inflation data beyond PCE, which has long served as the Fed’s preferred gauge. Warsh added that while the Fed will not telegraph the direction of rate policy, it will take whatever steps are necessary to achieve its 2% inflation target. As of Thursday’s close, traders continue to price in at least one rate hike by year end, though they have pared back bets on a further hikes next year.
Business:
Shares of Corning (GLW) fell -12% on Tuesday after it’s revenue guided below Wall Street estimates. Royal Caribbean Group (RCL) rose +5% after the company reported solid earnings lifted by strong demand and lower costs, though noting that geopolitical conflicts in the Middle East softened demand for Mediterranean cruises in Q3. Shares of Microsoft (MSFT) shares jumped +15% on Thursday after reporting +43% growth at its Azure cloud business, the highest since 2022. Shares jumped +$450 Billion in market cap, the largest in stock market history. The company noted that it now has over 30 million paid seats for Microsoft 365 CoPilot. Shares of Meta (META) declined nearly -8% as the social media giant missed expectations on earnings and reported a soft revenue guidance for the current quarter. Meta’s free cash flow plunged -91% year-on-year to $784 million as it continues to spend on AI investments.
Markets:
Commodities were mixed on the week. Precious metals advanced, with spot gold rising +1.25% and spot silver climbing +1.43%. Bitcoin eked out a gain of +0.95%, while the dollar fell -1.46% as inflation expectations rose following the FOMC meeting. WTI Crude declined -6% after the US and Iran paused strikes earlier in the week, though hostilities resumed on Wednesday, allowing crude to retrace some of its losses.
Stock Sector Performance
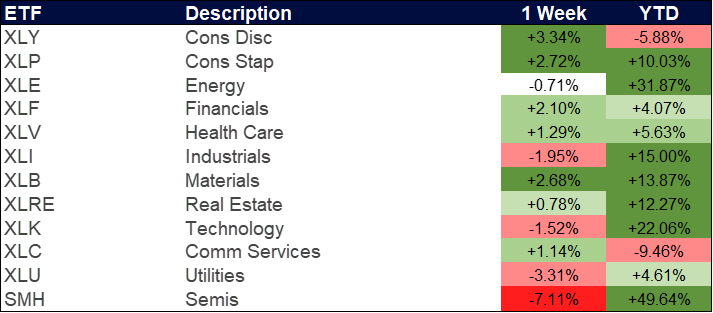
All performance figures and market events are sourced from Bloomberg as of market close 7/30/2026, using the prior Friday’s market open as the start date.
5404 Wisconsin Ave., Suite 330, Chevy Chase MD, 20815
(301) 799-9001
General Disclosure
This Presentation is for informational purposes only and does not constitute an offer to sell or the solicitation of an offer to purchase any security or investment product or services. The content of this Presentation is provided solely for your personal use and shall not be deemed to provide access to any particular transaction or investment opportunity.
This investment strategy is based on a model portfolio developed by Dynasty Wealth Management, LLC (“Model provider”), a registered investment adviser with the Securities and Exchange Commission. TritonPoint Wealth retains full discretion over the implementation, customization, and management of client accounts using this model. The Model provider does not manage client accounts, does not provide individualized investment advice, and is not responsible for investment decisions, performance outcomes, or suitability determinations. The Model provider receives compensation from the underlying investments. Outsourcing costs range from 2 – 4 bps (program fee) and can be discounted based on assets under management. Outsourcing includes investment management, trading, billing, and communications.
TritonPoint Wealth (TPW) does not intend the information in this Presentation to be investment advice, and the information presented in this Presentation should not be relied upon to make an investment decision. Any third-party information contained herein was prepared by sources deemed to be reliable but is not guaranteed.
TPW is a registered investment adviser with the Securities and Exchange Commission providing investment advisory and financial planning services. Any reference to the terms “registered investment adviser” or “registered” does not imply that TPW or any person associated with TritonPoint Wealth has achieved a certain level of skill or training. A copy of TPW’s current written disclosure (ADV 2A Firm Brochure) discussing our advisory services and fees is available for your review upon request. TPW, in addition to providing investment advisory and financial planning services, provides business consulting services. In connection with its business consulting services, TPW does not provide tax or legal advice.
This material is proprietary and may not be reproduced, transferred, modified, or distributed in any form without prior written permission from TPW. TPW reserves the right, at any time and without notice, to amend, or cease publication of the information contained herein. Certain of the information contained herein has been obtained from third-party sources and has not been independently verified. It is made available on an “as is” basis without warranty. Any recommendations, projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.